Last week, Bloom Energy (NYSE: BE) signed a 900-megawatt supply agreement with NTT DATA for onsite fuel cell power across global data centers. The same day, its stock fell 16%. On Wednesday, it surged 13%. That whipsaw is the entire story in one week: the business is producing real results at speed, but the stock is being priced as a pure AI-sentiment trade.
Why This Stock Now
Bloom reported Q3 2026 revenue of $1.236 billion, up 138% year over year. Product revenue crossed $1 billion in a single quarter for the first time, reaching $1.074 billion and representing 87% of total revenue. Non-GAAP operating income grew more than 500% to $285.7 million. The company raised full-year revenue guidance to $4.4 billion to $4.6 billion, its third guidance increase this year, implying roughly 122% growth at the midpoint. Customer deposits rose to $661 million from $78 million at the start of 2026, a figure that matters more than any one quarter’s cash flow.
The Business
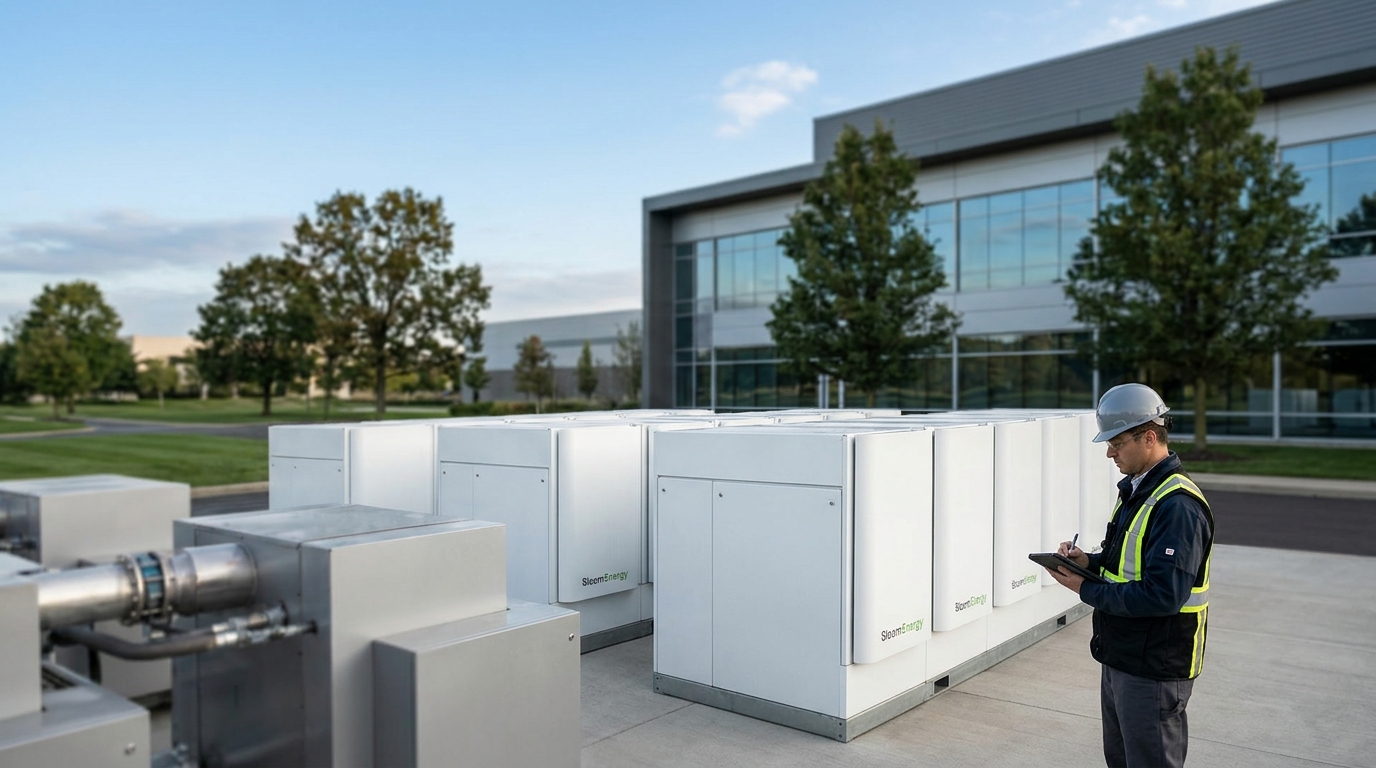
Bloom builds solid-oxide Energy Servers that sit on-site at data centers, bypassing the grid entirely. That is the core proposition. With utility interconnection queues stretching years into the future, hyperscalers and AI labs need power that shows up in months, not in a decade. Bloom’s CEO KR Sridhar said all major U.S. hyperscalers and over a dozen other operators have validated and approved Bloom’s technology for onsite power. The NTT DATA deal, 900 megawatts across multiple data center projects globally, could eventually reach gigawatt scale. Initial shipments start in 2027.
Year-to-date revenue of $3.05 billion is already about 50% above everything Bloom generated in all of 2025. The company carries about $2.49 billion in cash and cash equivalents. Gross margin reached 33.8% in Q3, up 453 basis points year over year.
Why Wall Street Is Paying Attention
After a Texas governor-elect pledged a moratorium on data center approvals and AI infrastructure stocks sold off sharply following the midterms, Bloom fell more than 40% from its June high. That overhang helps explain the selloff. What it does not explain is why the actual financial performance deteriorated, because it did not. CoreWeave’s strong Q3 report, released Tuesday, confirmed that AI infrastructure demand remains healthy, and AI power stocks including Bloom bounced hard on Wednesday as a result.
The onsite power theme is attracting more than just fuel cell specialists. AEP signed a 20-year Google contract for a 702MW fuel cell facility built on Bloom Energy technology, showing how utilities are now competing for the same data center power contracts.
What’s Driving the Opportunity
Three guidance raises in nine months, product revenue crossing $1 billion for the first time, operating margins expanding to 23.1%, and a customer deposit base that grew sharply in 2026 all point to a business executing ahead of its own forecast. The stock is still trading more than 40% below its peak while the fundamentals have continued to improve.
The NTT DATA deal and existing agreements with Oracle and others give Bloom a credible backlog. Its fuel cells run on natural gas, biogas, and hydrogen, which provides optionality as energy policy evolves.
What Could Go Wrong
Valuation is a real concern. One analysis places the intrinsic value near $58 per share against a recent price above $200. That is a wide gap. The company posted negative operating cash flow of about $27 million in Q3 despite record revenue, partly from the working capital requirements of scaling fast. Delivery timing is lumpy and largely determines where full-year results fall within guidance ranges, creating meaningful quarterly variance. Regulatory risk from data center moratoriums in Texas and elsewhere is not fully resolved. And Bloom’s stock has historically traded more on AI sentiment than on its own fundamentals, which cuts both ways.
The Bottom Line
Bloom Energy is not a speculative bet on a future market. It shipped $1.236 billion of revenue in a single quarter, raised guidance three times this year, and signed one of the largest onsite fuel cell agreements disclosed for data centers. The stock got caught in a political selloff that had nothing to do with its order book. Down 40% from its high with the demand story intact, the risk-reward has shifted meaningfully in favor of patient investors who are willing to absorb the volatility the market is currently attaching to anything AI-adjacent.