There are two Boeings operating simultaneously right now. One commands a Commercial Airplanes backlog of $612 billion covering more than 6,300 planes. The other delivered about 32 737 MAX jets in October, down from 43 in September. The question for investors is not which one is real. Both are. The question is which one wins.
Start with the demand side, because it is genuinely impressive. On November 4, Avolon finalized its purchase of 140 737-10 airplanes, a record 737 MAX order by a lessor that takes Avolon’s backlog to more than 240 unfilled orders. The purchase came about two weeks after the FAA certified the 737-10. Lessors have placed firm orders for more than 230 737-10s in 2026, five times the backlog for that variant at the end of 2025. Avolon CEO Andy Cronin described demand for new-technology aircraft as strong enough to anchor the company’s delivery pipeline well into the next decade.
That is not a niche signal. Boeing has said customers have ordered 7,350 737 MAX airplanes to date, and the company has said more than 1,450 of those orders are from lessors. Boeing says larger single-aisle aircraft represent the fastest-growing segment of commercial aviation. When an Irish lessor locks in 140 of your biggest narrowbody shortly after certification, that is the market speaking clearly about where it expects capacity needs to run for the next twenty years.
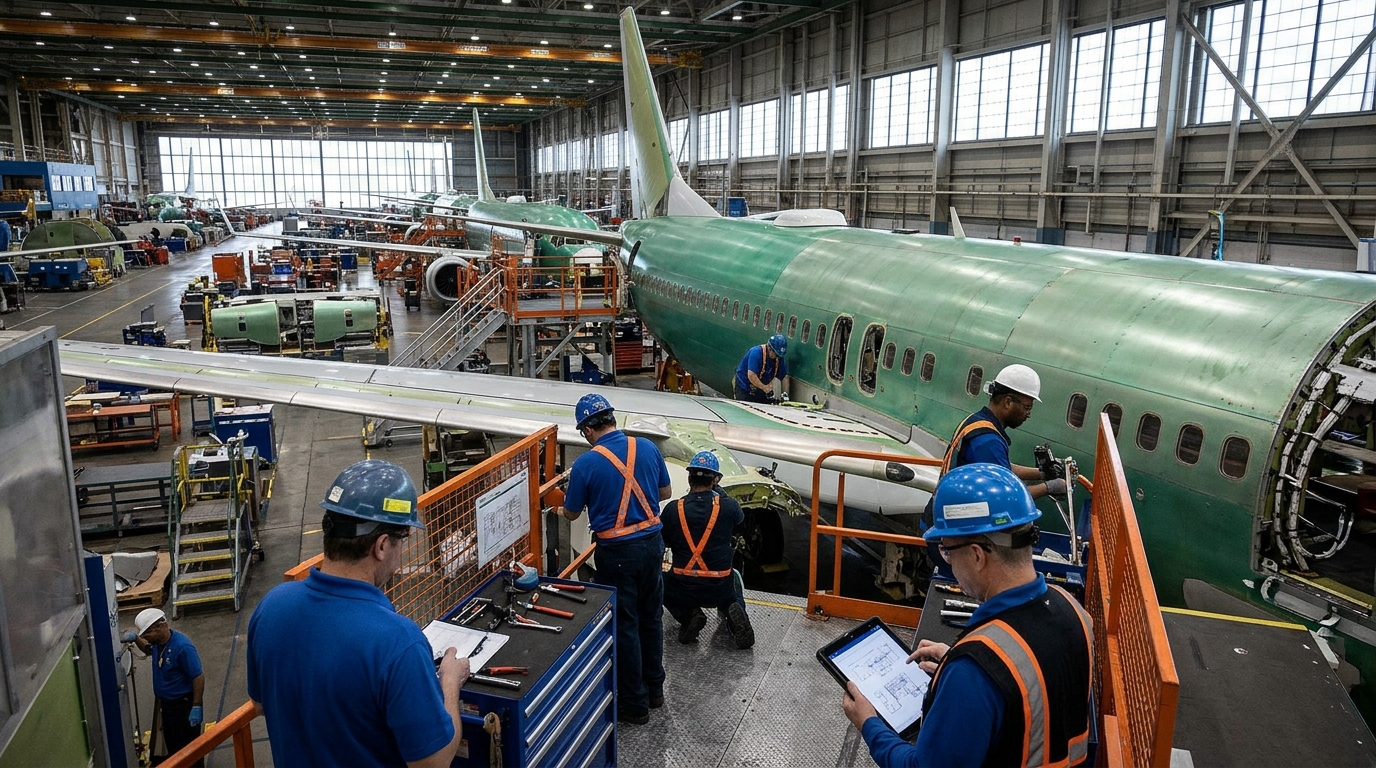
Now for the harder conversation. Delivery volume flows directly from monthly production rates and parts availability across the supply chain. The 737 MAX is Boeing’s main cash engine because each delivery triggers a large final payment, so the pace of handovers determines how much free cash flow the company books in a given quarter. Thirty-two jets in October does not pay the bills of a company carrying about $46 billion in total debt.
The 737 program will not hit its 2026 delivery target of about 500 jets, and the timeline to stable output at 47 a month has slipped into 2027. CEO Kelly Ortberg has said the company is not stable yet at 47 per month, and he has singled out wing flow as an internal pinch point. The company aims to reach a steady output of 47 jets a month in 2027 and 52 a month in the second half of 2027. Those goalposts have moved before.
BA was trading around $173 as of November 7, with a 52-week range spanning about $165 to $254. The stock is down more than 30% from that high. Twenty-eight analysts carry an average rating of Strong Buy with a 12-month price target of $233.35, implying roughly 35% upside from current levels. That consensus reflects confidence in the recovery, not confirmation of it.
The bear case is straightforward: Boeing keeps missing its own production schedules, the BCA division has posted operating losses so far in 2026, and October’s delivery slip raises real doubt about whether Q4 can generate the cash flow the bulls need to see.
The bull case is equally concrete. Operating cash flow reached $1.5 billion in Q3, and total company backlog grew to a record $745 billion. The 737-10 certification unlocks an entirely new delivery category. Boeing has said it built 737-7 and 737-10 planes before certification, and those will start delivering in early 2027. A single quarter of execution at 47 jets per month changes the cash flow picture materially.
Boeing is not the only industrial company where a record backlog and an execution gap are defining the trade. GE Vernova is navigating a similar tension between surging order demand and the capital decisions required to meet it.
BA earns a place on the short list today, but not comfortably. The backlog and the Avolon order confirm that demand is not the problem. Factory output is. Investors buying here are betting that the production ramp is delayed, not broken. That is a defensible bet at $173 with a $233 consensus target, but only if November and December deliveries show sequential improvement. Watch for Boeing’s official October delivery report, which should arrive in mid-November, to see whether the 32-jet estimate holds. That number tells you more about this stock’s near-term direction than any order announcement will.