November 6, 2026
Bonus Content: Duolingo’s Daily Users Jumped 29%. The Stock Surged 26%. Now What?
There’s a market signal that shows up around 9:35 AM that most traders completely overlook.
They’re watching RSI.
Moving averages.
Candlesticks.
Trying to figure out where the market is headed next.
Meanwhile, I’m watching what happens in the first few minutes after the opening bell.
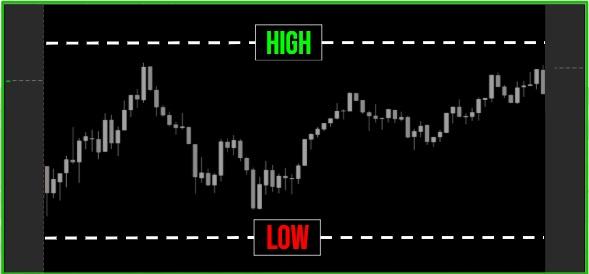
Because that’s where I’ve found a recurring pattern that can help identify key levels above and below the market.
I’ve spent years tracking this behavior.
And over the past two years, we’ve seen this approach produce 618 winning signals.
Now there’s a new test on the table.
Can we get to win #618 before the weekend?
I’ve set a challenge in motion to find out.
No trading guarantees, of course…
But I can show you the data behind the setup, the levels I’m watching, and exactly what I’m looking for as we make our run from #618 toward #620.
If you want to follow along the Challenge, I’ve laid everything out right here.
See you in the market,
Chris Pulver
Duolingo’s Daily Users Jumped 29%. The Stock Surged 26%. Now What?
Duolingo has not been a momentum stock in 2026. Through November 3, shares had fallen more than 50% over one year. Then Q3 results landed, and the market changed its mind in a single session.
Why This Stock Now
Duolingo stock jumped 25.99% to $161.27 on November 4 after the company released its third-quarter results the prior evening. The catalyst was not a profit surprise. Monthly active users rose 13% to 153.1 million, daily active users jumped 29% to 64.9 million, and paid subscribers increased 14% to 13.1 million. That DAU acceleration reversed a trend that had rattled investors all year.
Revenue reached $309 million against consensus estimates of roughly $303 million, for about 13.7% year-over-year growth. Q4 revenue guidance of $322 million at the midpoint came in about 2.3% above analyst consensus. Gross margin was 72.9%.
The Business
Duolingo is the leading mobile learning platform globally. In its annual filing, the company calls its flagship app the world’s most popular way to learn languages and the top-grossing app in the Education category on both Google Play and the Apple App Store. The platform now spans languages, math, and an English test business that serves visa applicants across dozens of countries.
AI-driven lesson personalization has made the app stickier, which helps explain the DAU acceleration from 23% growth in Q2 to 29% in Q3. On the earnings call, management said it expects Q4 gross margin to step down by about a point from Q3 as AI-related features reach more users and cost modestly more to serve at scale.
The Monetization Question
Here is where the bulls and bears diverge. Paid subscribers grew 14% to 13.1 million, and CFO Gillian Munson said subscriber growth would likely bottom in a couple of quarters as the company works through bookings from prior periods and rebuilds bookings growth. Duolingo has 153 million monthly active users. Converting more of them is what closes the gap between the user story and the financial one. That gap remains wide.
Major banks lifted price targets following the report but stayed at neutral ratings, saying more upside depends on stronger monetization. UBS raised its target to $180. The average price target across Wall Street analysts sits around the mid-$140s, well below Tuesday’s close. Duolingo also disclosed in its quarterly filing that a putative securities class action was filed on October 7, 2026, tied to allegations about monetization and AI-generated content and their effect on user growth. That overhang deserves monitoring. On the balance sheet, cash and short-term investments totaled about $1.37 billion at September 30, 2026, which does reduce near-term financial risk.
What Could Go Wrong
Duolingo increased its full-year revenue forecast modestly. That is a useful improvement, but much smaller than the 26% change in the stock price. At $161, the stock trades at roughly 6.7x trailing sales. That multiple prices in a monetization ramp that has not yet arrived. If subscriber growth bottoms later than management implies, or the class action gains traction, the user-to-revenue bridge will be hard to cross at current valuations.
The Bottom Line
DUOL collapsed from above $540 to roughly $133 before the earnings report. What makes the situation interesting is that the business did not collapse with the stock. Users, subscribers, and revenue have kept growing. The 29% DAU acceleration argues the product is working. The monetization execution is what Q4 and Q1 2027 will test, and that is the number that decides whether Tuesday’s rally was the beginning of a recovery or a one-day overshoot.