The timing is almost designed to test an investor’s nerve. Four days after remibrutinib’s relapse data landed below what analysts needed to see, Novartis reported a quarter that showed the machine underneath the pipeline still runs well.
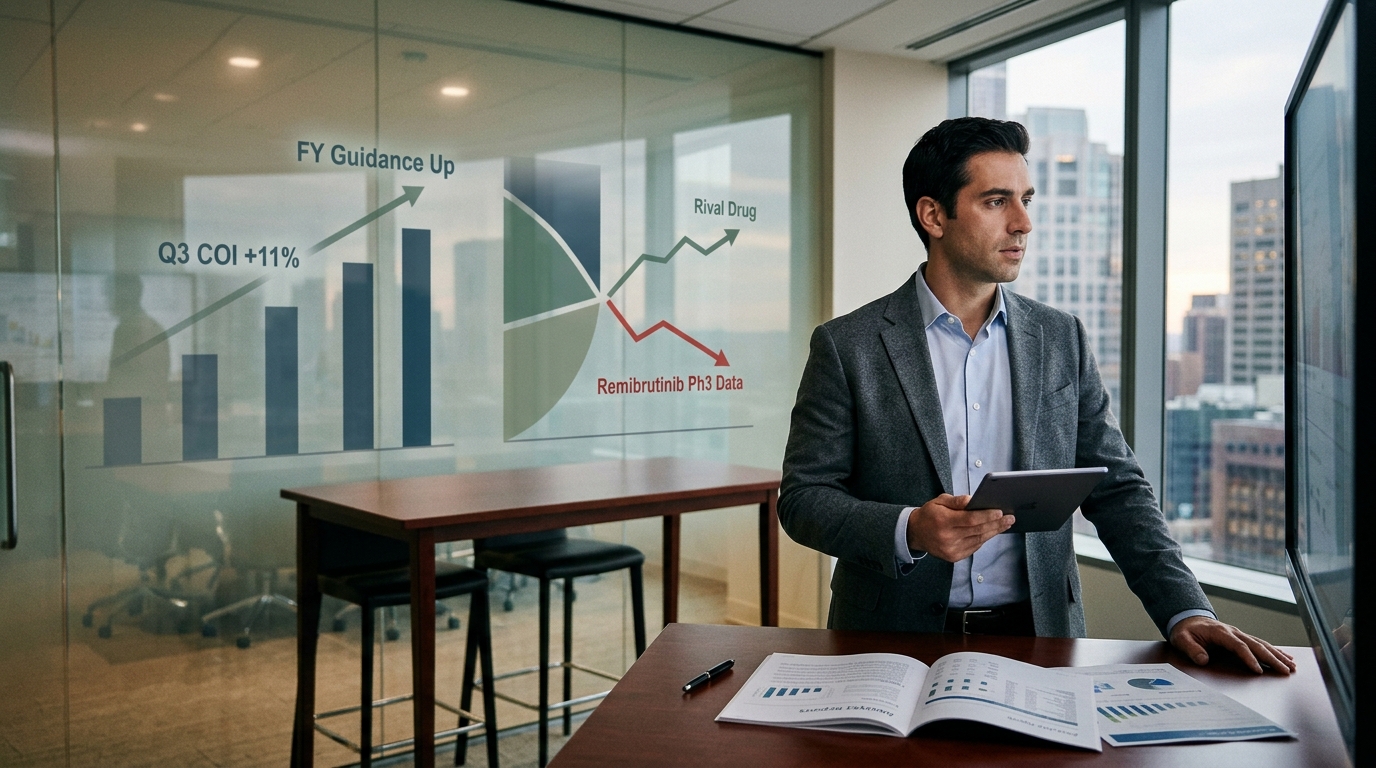
On October 27, Novartis delivered core (non-IFRS) EPS of $2.46, beating estimates by $0.22, while revenue of $14.52 billion slightly missed expectations despite a solid year-over-year increase. More importantly for anyone thinking about this as a long-term holding, core operating income increased 11% to $6.04 billion. The company raised its 2026 profit outlook even as it booked a $1.9 billion partial impairment charge on del-desiran, with core operating income now expected to be in line with last year or up low single digits at constant currencies, versus a low single-digit decline before.
That guidance flip is the number that matters most today. It signals that the operational engine, not the pipeline lottery, is doing the heavy lifting.
What Actually Drove the Beat
Kisqali rose 37%, Kesimpta 22%, Scemblix 67%, and Leqvio 63%, offsetting generic erosion, what CEO Vas Narasimhan called proof of “the replacement power of the business.” Core operating income margin reached 41.6%. That is not a pharmaceutical company in distress. That is a company extracting significant cash from a portfolio of drugs with real commercial momentum.
The headline GAAP figures looked far worse: reported operating income fell 59% to $1.843 billion, and reported EPS dropped 69% to $0.63, weighed down by higher R&D and the del-desiran impairment. Investors who stop at the GAAP line will misread this quarter entirely.
The Remibrutinib Problem in Plain Terms
The MS data presented in Toronto last Friday was not a complete failure. Remibrutinib reduced the annualized relapse rate by 35.2% and 31.2% in two Phase 3 studies versus Sanofi’s Aubagio. The trouble is the competitive frame: analysts had expected a reduction of 45% to 60%, and Roche’s rival drug posted 55% in pooled Phase III data.
Peak sales estimates of about $4 billion for the MS indication may now be too optimistic, analysts said, after the disappointing efficacy results. That is a real problem for the long-term revenue bridge. Novartis was banking on remibrutinib’s success following trial setbacks for its heart drug pelacarsen and muscle weakness therapy del-desiran. A third program underperforming relative to expectations in the same year adds pressure on the business development team to find external assets.
The Defensive Case, and Its Limits
Here is what the Q3 results confirm: Novartis offers a dividend yield around 3%. Free cash flow did decline 18% to $5.1 billion, which bears watching, but the core business generated enough to lift full-year guidance in the same quarter it absorbed a write-down worth nearly $2 billion.
The risk is forward-looking. The base business funds the dividend comfortably. What it now needs to fund is a pipeline gap that three setbacks in one year have widened considerably. Novartis has already been shopping aggressively, including a large 2026 acquisition that pushed up net debt. The question investors face is whether a 41.6% core operating margin can keep generating the cash needed to buy what the internal labs have not yet delivered.
Wealth-Building Takeaway
Novartis today is a case study in separating operational quality from pipeline risk. The operating income number says the core franchise is worth owning. The remibrutinib disappointment says the premium for pipeline optionality should be held more lightly than it was a month ago. For investors in defensive healthcare positions, that combination argues for sizing Novartis as a dividend-anchored holding rather than a high-growth bet, watching deal flow closely, and recognizing that guidance upgrades built on commercial execution tend to be more durable than those built on trial data that has yet to be filed with regulators.