Here is a question worth sitting with: who is the real buyer of Appalachian natural gas in 2026? Not utilities haggling over Henry Hub. Increasingly, it is data center operators who need firm power and will pay power-linked prices to get it. EQT just made a $50 billion bet on that shift.
What Changed
EQT Corporation and Range Resources announced a definitive merger agreement under which EQT will acquire Range in an all-stock transaction, creating America’s leading natural gas company with a pro forma enterprise value over $50 billion. Each outstanding share of Range common stock will be exchanged for 0.987 shares of EQT common stock, with EQT’s existing shareholders expected to own approximately 73% of the combined company and Range’s shareholders approximately 27%. Based on the companies’ October 23, 2026 closing prices, the implied offer value works out to about $54.91 per share, a roughly 20.6% premium to Range’s October 23 close.
As a result of the announced transaction, EQT and Range canceled their previously scheduled Q3 2026 earnings conference calls on October 28, 2026, though both companies still plan to issue their Q3 earnings results after the market close on October 27, 2026. The deal was announced on October 26, 2026, and the companies held a joint call at 8:00 a.m. ET that day to field questions about the transaction.
The Investment Thesis
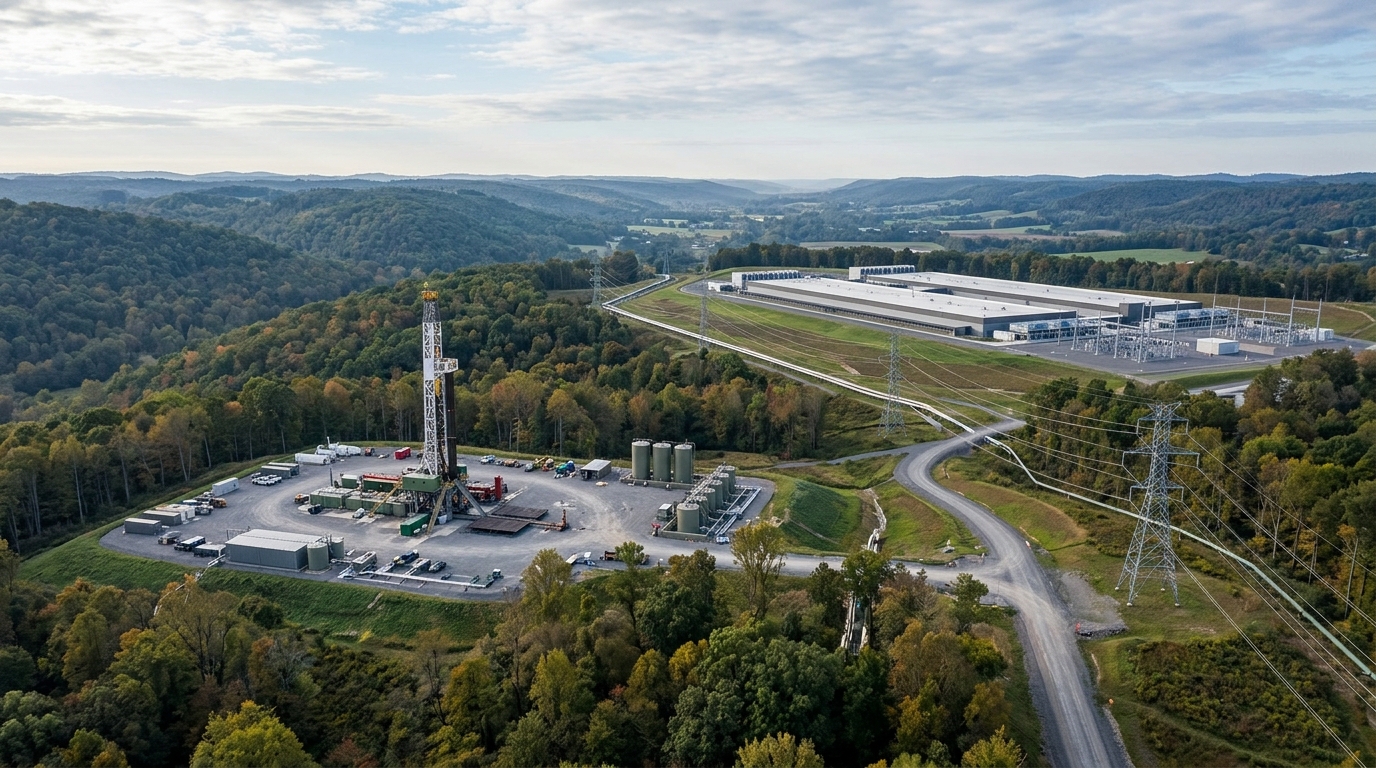
The combination brings together two of the highest-quality natural gas assets in North America, creating America’s largest and only vertically integrated natural gas producer with leading inventory depth and low-cost structure. The scale numbers are significant. The merged producer will hold nearly 3 million net acres in the Appalachian Basin, more than 30 years of drilling inventory, and more than 3,700 miles of midstream pipeline, while EQT says the deal will cut its unlevered free cash flow breakeven to below $2 per million British thermal units.
That sub-$2 breakeven is the number that matters most for through-cycle investors. It means EQT can generate free cash flow even if Henry Hub stays depressed, while capturing upside through premium contracts when power demand tightens the basin.
The Data Center Angle
The deal is not simply a scale play. EQT signed a 10-year definitive agreement with Competitive Power Ventures to supply 325,000 Dth/d of natural gas to the CPV Shay Energy Center in West Virginia, with pricing linked to PJM power prices, providing a substantial uplift relative to in-basin pricing. EQT has also said it had secured offtake agreements covering 1.4 Bcf/d of gas supply for data center and power projects.
EQT has discussed potential Appalachian gas demand rising to 25 Bcf/d versus a prior figure near 20 Bcf/d, based on comments made on the deal-related conference call. Adding Range’s acreage and inventory gives EQT the resource base to actually honor those decade-long commitments. The data center has become the marginal buyer of Appalachian gas, and it does not care about Henry Hub. It cares about getting power and will pay the power price to get it. The producer who can offer firm ten-year supply at a plant next door can write a contract off that power price instead of off a commodity benchmark.
Synergies and Cash Flow
EQT expects $325 million in base annual synergies within two years, with a path to more than $600 million long-term. The company projects roughly $20 billion in cumulative free cash flow over five years at recent strip pricing. The companies expect the deal to close in the first quarter of 2027.
The Risks
EQT shares fell on the announcement, the familiar penalty acquirers pay in all-stock deals. Regulatory clearance is not certain, and the deal still requires approval from shareholders of both companies. Competitors Antero Resources (AR) and CNX Resources (CNX), along with Coterra Energy (CTRA), remain independent and could consolidate further, altering basin dynamics. And the entire thesis depends on data center demand staying firm: the front-month Henry Hub futures contract fell to around $2.51 per MMBtu on October 26, 2026, a reminder that the commodity market is not yet pricing the demand surge EQT is banking on.
What to Watch Tonight
When Q3 results hit after the close today, investors should watch two things beyond the headline figures: first, whether EQT discloses any new power-linked supply agreements signed in the quarter; second, what management says about the pace of data center contract negotiations across the combined acreage. If the new deals are larger and priced above Henry Hub, the case for owning the combined company sharpens considerably. If the quarter shows execution softness heading into a complex integration, EQT’s diluted shareholders will ask whether Range’s inventory was worth the price.