October 20, 2026
Bonus Content: NFLX Is Down 25% This Year. Tonight Decides the Tone.
Below is an important message from one of our highly valued sponsors. Please read it carefully as they have some special information to share with you.
Hi, James Altucher here.
I’m reaching out today to relay epic three words, recently spoken by Elon Musk.
Infinite.
Money.
Glitch.
It sounds insane…
But that’s what Elon is calling a groundbreaking new class of technology about to take the world by storm.
I have put together a short presentation on what it is and why I believe this could be the biggest wealth event of our lifetime.
[ → Watch the presentation by October 21 ]
James Altucher
PS: I’m giving away a free report to anyone who watches this presentation today. It details Elon’s Musk’s unprecedented trillion-dollar compensation package and identifies the companies he NEEDS to hit his incentives. Just click here to watch the free video, and I’ll show you how to claim it. No credit card needed.
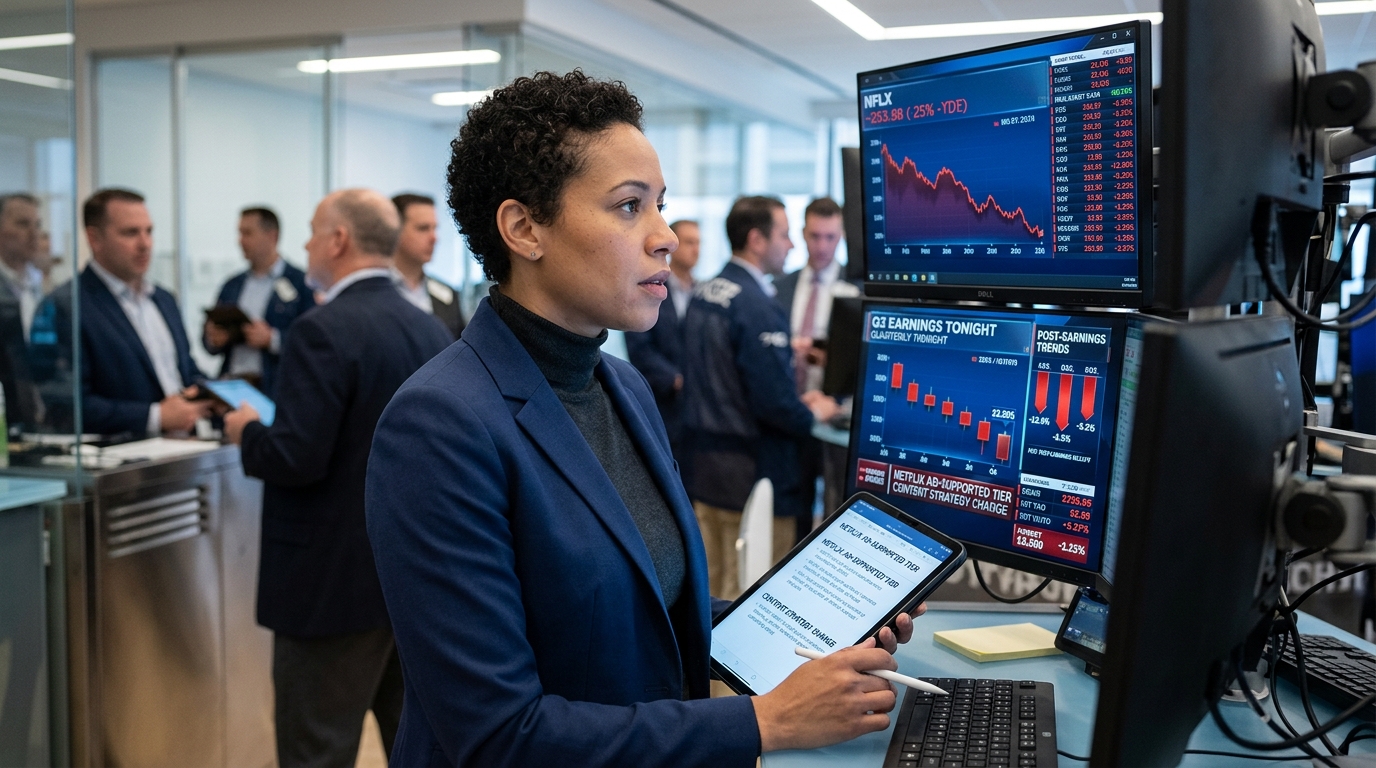
NFLX Is Down 25% This Year. Tonight Decides the Tone.
Netflix has now fallen in the session following each of its last five quarterly earnings releases. The average loss across those five reactions was approximately 6.9%, with the steepest being a 10.1% drop after October 2025 earnings, followed by a 9.7% decline in April 2026. Tonight is the sixth attempt to break that streak.
The stock closed Monday at $69.85, against $93.76 at the end of 2025. That is a 25% drawdown in under a year, and the company has not been quiet about the pressure showing up underneath the financials.
Why This Stock Now
When five consecutive earnings reports generate negative stock reactions despite generally solid fundamentals, the market is telling you something beyond the quarterly numbers. In Netflix’s case, the signal is that growth is decelerating and Wall Street needs to see a credible second act.
Last Wednesday, Netflix said it will cut 6% of its workforce, about 1,000 employees, its largest reduction since 2022. On Thursday, Netflix named former Disney executive Peter Rice as its next chief content officer, effective October 26, replacing Bela Bajaria. Two structural moves in two days, just before an earnings report, is not coincidence. Management is trying to reset the investor conversation before the numbers land.
The Business
Netflix operates the world’s largest paid streaming service, with membership crossing 325 million by the end of 2025. For full year 2025, the company delivered $45.2 billion in revenue, up 16% year over year, with advertising revenue rising more than 2.5x to over $1.5 billion.
Advertising is where the next leg of growth lives. Management has said it expects a rough doubling of ad revenue to approximately $3 billion in 2026. That target, if achieved, would represent roughly 6% of total revenue. Modest today, but the trajectory matters far more than the share.
What Wall Street Expects Tonight
Netflix will post its third quarter 2026 results and business outlook at approximately 1:01 p.m. Pacific Time. The key is whether the results and outlook confirm that membership gains, pricing, and advertising are still enough to carry growth and margins.
Subscriber net additions, average revenue per member, and operating margin expansion are the three metrics analysts will scrutinize most closely. The upside, if any, will come from ad revenue trajectory and Q4 guidance.
What Could Go Wrong
Five firms cut their price targets on Netflix in October: Wedbush to $90 from $105, BMO Capital to $125 from $135, KeyBanc to $85 from $92, Barclays to $70 from $80, and Morgan Stanley to $80 from $83. The price target range itself tells you how wide the disagreement is about what Netflix is worth.
The decline reflects growing investor concerns about viewing engagement, competition from YouTube and other streaming services, and whether Netflix can maintain strong growth as its subscription business matures. A leadership shake-up just before results can be read as confidence or as crisis management. Tonight will clarify which.
The Bottom Line
At $70, Netflix trades at roughly 21x consensus 2026 earnings, a meaningful compression from where it spent most of 2025. The operational case for the stock is not broken: the company has reiterated that it continues to project 2026 revenue of $50.7 to $51.7 billion and an operating margin of 31.5%. If Q3 confirms those guardrails are intact and management offers credible Q4 guidance, the stock has room to recover sharply from a depressed base. The risk is that the sixth consecutive negative reaction simply continues a pattern the market has already priced in as normal for NFLX. One of those two outcomes arrives tonight.